Value & negotiation · Essay 125
How Small Businesses Can Protect Sales and Profit Margins When American Customers Start Spending Less
The Accidental Salesman Editorial Desk · 15 min read · Published 11 November 2026
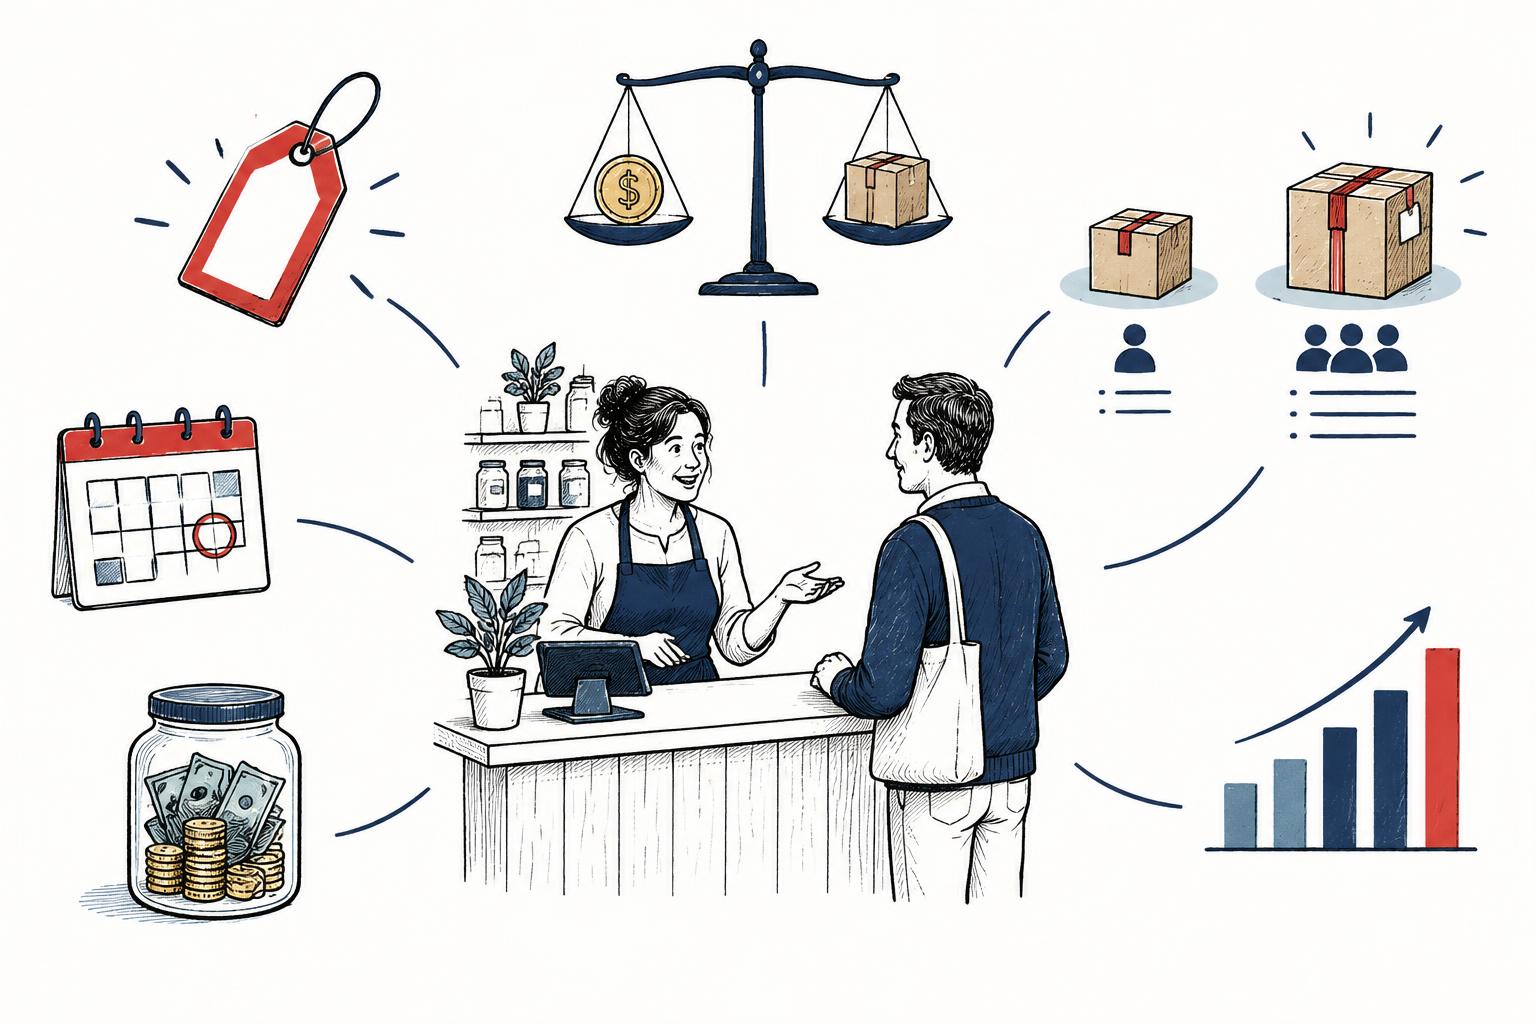
The first sign is often a different kind of conversation. A regular customer asks whether the repair can wait. A prospect likes the proposal but wants a smaller version. Someone who used to order every month now orders every six weeks. The business is still getting attention, but attention is taking longer to become money.
For a small-business owner, the instinct is understandable: lower the price, send more promotions and keep the team busy. Sometimes a targeted offer helps. Sometimes it converts a manageable slowdown into a profit problem. A full calendar is little comfort if each job leaves too little to pay the rent, replenish stock and cover payroll.
The better objective is not to defend every dollar of revenue at any cost. It is to preserve worthwhile customer demand while keeping the economics of serving that demand intact. This guide explains how US small businesses can respond when their customers become more cautious, without assuming that all Americans are cutting spending or that a recession is inevitable. Official evidence provides context; the calculations and business scenarios below are illustrative, not client results.
1. Separate a cautious customer base from a national spending collapse
As of this article’s 11 November 2026 review, the Census Bureau’s September advance report showed US retail and food services sales rising 0.8% from August and 6.3% from a year earlier. Those estimates were adjusted for seasonal, holiday and trading-day differences, but not for price changes [R151]. They do not support declaring a nationwide spending collapse. Nor do they tell you that your particular customers are buying more units, purchasing more often or feeling financially comfortable.
Retail and food services figures are not a complete measure of household consumption. A national total can also conceal differences between categories, places and customer groups. A local discretionary retailer and an essential repair business can face very different demand conditions in the same month. Dollar sales can rise while customers trade down or pay higher prices for fewer items.
There is nevertheless evidence of pressure on small businesses. The Federal Reserve Banks’ 2026 Report on Employer Firms, based on the fall 2025 Small Business Credit Survey, identified reaching customers and growing sales as the most commonly reported operational challenge. Rising costs were the most common financial challenge [R152]. The survey covered 6,525 employer firms through a nationwide convenience sample, not a random sample; it is context from 2025 respondents, not a live November 2026 consumer-spending measure.
Treat the title’s “when” as a business condition to diagnose, not a macroeconomic forecast. If your customers are spending less, you need a response even when the national headline looks healthy. If your sales are falling because estimates arrive late or a competitor offers a better service, blaming the economy will postpone the necessary fix.
2. Find out what is actually falling
Break the problem into customer count, purchase frequency, average order value and product or service mix. A decline in any one can reduce revenue, but each calls for a different action. Fewer first-time customers points toward acquisition or conversion. Longer gaps between repeat orders point toward changing usage, budgets or retention. A lower average ticket may mean customers are choosing a smaller package rather than leaving.
Compare equivalent periods and customer groups. Account for holidays, weather, opening hours, promotions, refunds and stock shortages. A business that was closed for several days should not interpret a lower monthly total as a pure demand signal. A service business should distinguish fewer inquiries from fewer estimates accepted and fewer jobs actually completed.
Speak to a small, varied selection of customers, including people who postponed or declined. Ask, “What changed in the decision?” and “Which part still matters enough to do now?” Separate affordability, uncertainty about value, timing, a competing offer and dissatisfaction. Do not classify every “not now” as a price objection. Sales-listening research links listening with adaptive selling and relationship and performance measures; it is not proof that one script will reverse a slowdown [R9].
Keep a simple decision log with the customer’s explanation, the offer considered and the next agreed step. That record is more useful than an owner’s impression that “everyone wants a discount.” It can show whether the business needs a smaller offer, a clearer explanation, a delivery improvement or a different audience.
3. Know the difference between sales, gross margin and contribution
Revenue is the amount sold. Gross profit is revenue less cost of goods sold under your accounting policy, and gross margin is gross profit divided by revenue. Contribution is revenue less the costs that vary with the sale. These are related but not interchangeable. A payment-processing fee or a variable sales commission may reduce contribution without being classified as cost of goods sold.
For pricing decisions, identify the costs an additional order actually creates: materials, incremental fulfillment labor, transaction fees, freight, commissions, expected returns and foreseeable rework. Do not assume every labor cost varies immediately with volume. Salaried staff and guaranteed shifts may remain payable when orders fall. Your accountant can help keep management calculations consistent with the financial statements.
The SBA’s break-even calculator expresses break-even units as fixed costs divided by selling price minus variable cost per unit [R153]. That is a useful starting point for a reasonably stable, single-offer calculation. Multiple products, changing capacity, step costs and uncertain demand require more careful modeling. If the price does not exceed variable cost, extra units do not move the business toward covering fixed costs.
Illustratively, a product priced at $100 with $60 of variable costs contributes $40. At $8,000 of monthly fixed costs, 200 such units cover those fixed costs before other unmodeled obligations. This is not a target for every business. It shows why knowing the money left from a sale matters more than simply knowing its price.
4. Calculate the price of a discount before announcing it
Using the same illustrative $100 price and $60 variable cost, a 10% discount reduces price to $90 and contribution to $30. Price has fallen 10%, but contribution per unit has fallen 25%. To preserve $4,000 of contribution previously earned on 100 units, the business needs approximately 134 discounted units, assuming unchanged unit costs, sufficient capacity and no additional promotional expense. That is roughly 34% more units, not 10% more.
A larger response is possible, but it must be earned. If most discounted buyers would have purchased anyway, the promotion mostly transfers margin to existing demand. If the extra orders require overtime, free shipping or more returns, the unchanged-cost assumption fails. Evaluate incremental contribution after campaign costs and displaced full-price purchases, not just coupon redemptions.
Discounting can be sensible for clearly defined purposes: perishable stock, genuinely surplus capacity, a measured acquisition test or a concession exchanged for lower delivery cost. It should not become the automatic response to every hesitation. Set an owner-approved limit and an end condition before the offer goes out.
A concession should buy something commercially useful and appropriate: a simpler scope, consolidated delivery or scheduling flexibility. Do not pressure customers into advance payments that the business cannot safely honor. A discount for paying an invoice early also has a financing cost; compare that cost with the actual cash benefit rather than treating it as free liquidity.
5. Offer a smaller commitment without quietly degrading the product
A cautious buyer may still need the outcome but cannot justify the original commitment. Create a genuinely smaller offer: fewer deliverables, a basic configuration, a limited first phase or a lower service frequency where that remains safe and effective. Preserve the essential quality and say plainly what is excluded.
An illustrative home-service company might separate an essential repair from optional improvements. A small agency might offer a tightly scoped diagnostic before a larger engagement. A specialty retailer might stock a lower-priced item that meets a narrower need rather than discounting the premium item for everyone. These are proposed offer designs, not reported customer cases.
Price the smaller version from its actual delivery requirements. A package at half the price is not economically smaller if it still requires nearly all the setup, travel and administration. Include minimum order costs and the burden of many small transactions. An apparently accessible option can consume more capacity per dollar than the original.
Make comparisons transparent: total price, scope, timing, support and limitations. Do not remove essential safety work, make the basic offer deliberately unusable or hide mandatory charges until checkout. The goal is to let a customer choose a suitable commitment, not to make the headline price look lower than the amount they must pay.
6. Make value concrete instead of defending price with slogans
“We provide better quality” is difficult for a worried customer to evaluate. Explain the difference they can inspect: the work included, the materials specified, the response commitment you can actually meet, or the steps that reduce inconvenience. Connect each difference to the buyer’s stated concern.
If a competitor is cheaper, ask what is included in both proposals. A valid comparison may reveal a scope difference; it may also reveal that your price is simply too high for what this customer needs. Do not invent a competitor’s shortcomings or manufacture savings to win the argument. Sometimes the honest recommendation is the smaller option, a later date or another provider.
Reduce uncertainty where you can: a clear estimate, a credible timetable, understandable cancellation terms and a named person for questions. Use genuine, authorized evidence rather than invented testimonials. When a return or warranty commitment is offered, include its expected cost in the economics and explain its conditions.
A useful follow-up answers the unresolved decision question. “Here is the revised scope you asked for” is more valuable than “Just checking in again.” The guide to trust-first sales follow-ups explores how preparation and timing can support that conversation without increasing unwanted message volume.
7. Protect repeat business by remembering the last promise
Existing customers deserve attention, but retention is not automatically cheap or profitable. Review repeat contribution, service burden, complaints and payment behavior. A loyal account that needs unusually costly customization may require a scope discussion, not another unconditional discount.
Reach out around genuine needs: scheduled maintenance, replenishment, an unresolved service issue or a previously agreed decision date. Ask whether priorities have changed. A customer who is buying less may appreciate a sensible adjustment more than an upsell. Respect a request to pause and keep access to a person straightforward.
Consider limited benefits that cost less than their value to the customer, such as combining deliveries or providing a convenient scheduling option. Capacity still has a cost, and benefits should not disadvantage other customers or promise availability you cannot deliver. Evaluate loyalty rewards through repeat contribution after reward costs, not enrollment counts.
For US commercial email, the FTC’s CAN-SPAM guide sets requirements including accurate sender information, a valid physical address and an opt-out mechanism; an existing relationship is not a blanket exemption [R104]. Calls and texts raise separate rules. A slowdown is not a reason to ignore channel requirements or repeatedly contact people who have declined.
8. Cut waste before cutting the experience customers pay for
Review the practical sources of margin leakage: duplicate software, avoidable freight, spoilage, excessive product variety, repeated scheduling changes, estimation errors and rework. These can be less visible than wages or rent, but addressing them may protect both cost and service quality.
Discuss supplier terms before simply switching to the cheapest source. A lower unit price can be offset by longer lead times, larger minimum orders, more defects or cash tied up in stock. Confirm landed costs and contractual responsibilities. The Federal Reserve survey’s cost findings are a reason to inspect exposure, not evidence that every firm needs the same sourcing change [R152].
Simplify where customers do not value complexity. Standardizing a service option or reducing slow-moving variants can make delivery more predictable. Test the consequences rather than assuming every reduction is harmless. Do not cut the knowledgeable employee, quality check or support channel that makes customers choose you.
Schedule staffing against realistic demand while honoring employment obligations and preserving the ability to serve promised work. The purpose is not to push every cost onto employees or suppliers. It is to remove work that consumes resources without improving the outcome.
9. Treat cash flow as a separate survival question
A sale recorded today may not pay next Friday’s payroll. Inventory can absorb cash before it produces revenue. Debt principal can use cash without appearing as the same kind of operating expense. A business can be profitable on paper and still run short of money.
Build a rolling weekly cash forecast. A suggested 13-week view is an editorial planning convention, not a federal requirement. Enter opening cash, realistically timed receipts and known payments, including payroll, taxes, rent, suppliers and debt service. Keep a slower-sales case and a delayed-collections case beside the base case. Update assumptions rather than carrying forward optimistic receipt dates.
The SBA’s financial-management guidance emphasizes bookkeeping and responsibility for receivables, payables, available cash and bank reconciliation [R154]. Invoice promptly, make payment instructions clear, resolve disputes early and follow up courteously. A deposit can help fund committed work, but it creates delivery and possible refund obligations; it is not spare profit.
If a forecast reveals a gap, speak early with an accountant, lender or qualified adviser about realistic options. Compare financing by total cost, repayment timing and obligations, not merely the speed of approval. Borrowing cannot repair an offer that consistently loses money, and fixed repayment demands can worsen a volatile sales pattern.
10. Measure marketing by profitable customers, not busy channels
When budgets tighten, keep the path from spending to completed sales visible. Record source, qualified inquiries, accepted offers, fulfilled orders, contribution and collection timing. Compare similar cohorts over a period long enough for the buying cycle, and include cancellations and refunds.
For an illustrative campaign, 20 orders at $40 contribution generate $800 before a $500 campaign cost, leaving $300 before fixed overhead. If a discount cuts contribution to $30, those same 20 orders generate $600 and leave $100. The order count has not changed, but the campaign’s economics have. Neither figure is net business profit, and the calculation assumes the orders are incremental rather than displaced purchases.
Retain low-cost channels that genuinely help buyers decide: clear local listings, reliable referral relationships, useful product information and prompt inquiry handling. Low cost is not zero cost; include staff time. Avoid stopping a channel solely because its last-click reporting is weak when it may support discovery or trust.
AI can help summarize approved notes or draft clearer answers, but a new tool is another cost and review obligation. Use it for a specific bottleneck, not as a promise to replace lost demand. The small-business AI conversion guide explains how to measure total effort and actual commercial outcomes.
11. Run a manageable 30-day response, not ten simultaneous experiments
In the first week, establish the baseline: customer count, frequency, average order, mix, contribution and cash commitments. Read recent lost-sale notes and speak to a varied customer sample. Identify one demand problem and one cost problem that the business can act on.
In the second week, test one offer change with clear scope and approved pricing. Keep a comparable existing offer available where practical, and record who sees each version. Do not mistake a before-and-after comparison for causal proof; seasonality, customer mix and competitor activity can explain differences.
In the third week, remove one recurring source of waste and review collections. Give the team a clear price-objection response and a rule for escalating concessions. Inspect a handful of real conversations for accurate promises and useful next steps rather than rewarding persistence alone.
In the fourth week, review contribution per order, total contribution, conversion, delivery burden, complaints and cash movement. Keep changes that work, revise ambiguous ones and stop those that merely add activity. Thirty days may reveal operational problems but be too short to judge a long buying cycle. Continue tracking outcomes without declaring a premature turnaround.
12. Questions owners should ask before the next promotion
Should we lower every price? Not without evidence about the obstacle and the contribution lost. A narrower offer or a more useful explanation may address the problem. A targeted discount should have an economic purpose, a limit and a way to evaluate incremental demand.
Should we raise prices if our own costs rise? Possibly, but test customer value, alternatives and contribution rather than passing through every increase mechanically. Explain meaningful scope and price changes clearly. A price increase that loses little volume may help; one that drives away valuable repeat demand may not.
Is keeping revenue stable enough? No. Revenue can be maintained through concessions, expensive fulfillment or unfavorable payment terms. Examine total contribution, operating profit and cash separately. Nor is a higher margin percentage sufficient if total contribution falls too far to cover fixed commitments.
When should we get outside help? Before repeated cash gaps, unpaid obligations or uncertain pricing decisions become emergencies. An accountant or qualified adviser can help test scenarios and distinguish a temporary demand issue from a structural cost problem. Sector-specific tax, financing, consumer and employment questions need advice for the actual circumstances.
13. The aim is a business customers can still choose and you can still afford to run
Customers who are spending less do not necessarily stop caring about quality, convenience or reliability. They become more selective about which commitments deserve their money. A smaller business can respond well because it is close enough to hear those changes and adjust an offer without redesigning an entire corporation.
That advantage disappears when the response is indiscriminate discounting, weaker delivery or relentless outreach. Listen first. Make the choice clearer. Price the actual work. Remove waste that customers do not value. Preserve promises that they do.
There is no universal promotion that protects every business from weaker demand. There is a better decision discipline: know what changed, know what each sale contributes, test the smallest useful adjustment and keep cash visible. It will not guarantee growth. It can help an owner avoid sacrificing the business’s future just to make this month’s sales total look reassuring.
Put it to work
A practical next step
Review equivalent recent sales periods and ten varied customer decisions. Separate changes in customer count, frequency, order value and mix. With your accountant, calculate contribution for the main offers and model one discount at unchanged and higher delivery costs. Test one clearly scoped alternative, track incremental contribution and customer response, and update a weekly cash forecast. Continue only if the change protects worthwhile demand without unacceptable service, margin or cash costs.
Proposed practice, not a completed experiment. Illustrations are not client testimony.
Sources & limits
Official living release page reviewed 11 November 2026: September sales rose 0.8% month over month and 6.3% year over year, not adjusted for price changes. Advance estimates are revisable; this is not all household consumption, local demand or proof of increased purchase volume. Page will move to subsequent releases.
Fall 2025 nationwide convenience sample of 6,525 employer firms with 1–499 employees, not a random sample or live November 2026 consumer measure. Sales and cost challenges are reported firm experiences; findings do not establish a universal spending contraction or causal effect of any recommended response.
Official fixed-cost divided by price-minus-variable-cost framework. Article examples are editorial calculations, not SBA customer results or guarantees; product mix, capacity, changing costs, tax and cash obligations can require a more detailed model.
Official general guidance on bookkeeping, cash, receivables, payables and cost-benefit analysis. Not individual accounting, lending or legal advice; the proposed 13-week cash view and 30-day response are editorial conventions, not mandated SBA periods.
Commercial-email guidance, including B2B messages, ten-business-day opt-out honoring and a 30-day operational opt-out mechanism. Verified via indexed official text because direct retrieval was restricted; not complete privacy, calling, texting or sector-specific legal advice.
Meta-analytic model of salesperson listening; associations and synthesized relationships do not establish that an example email causes better outcomes.
Editorial synthesis published 11 November 2026. Research is linked above; examples and the practical exercise are editorial applications, not reported outcomes.